
Some people love tracking every category. If you’re reading this, you’re probably not one of them, which makes pay yourself first the easier route.
That’s fine. You can still save money without logging every coffee. The pay yourself first budget flips the usual order. Instead of saving whatever is left at the end of the month, which is often nothing, you move savings out the day you get paid.
Then you pay the bills. Whatever remains is yours to spend, no spreadsheet required.
- How pay yourself first works
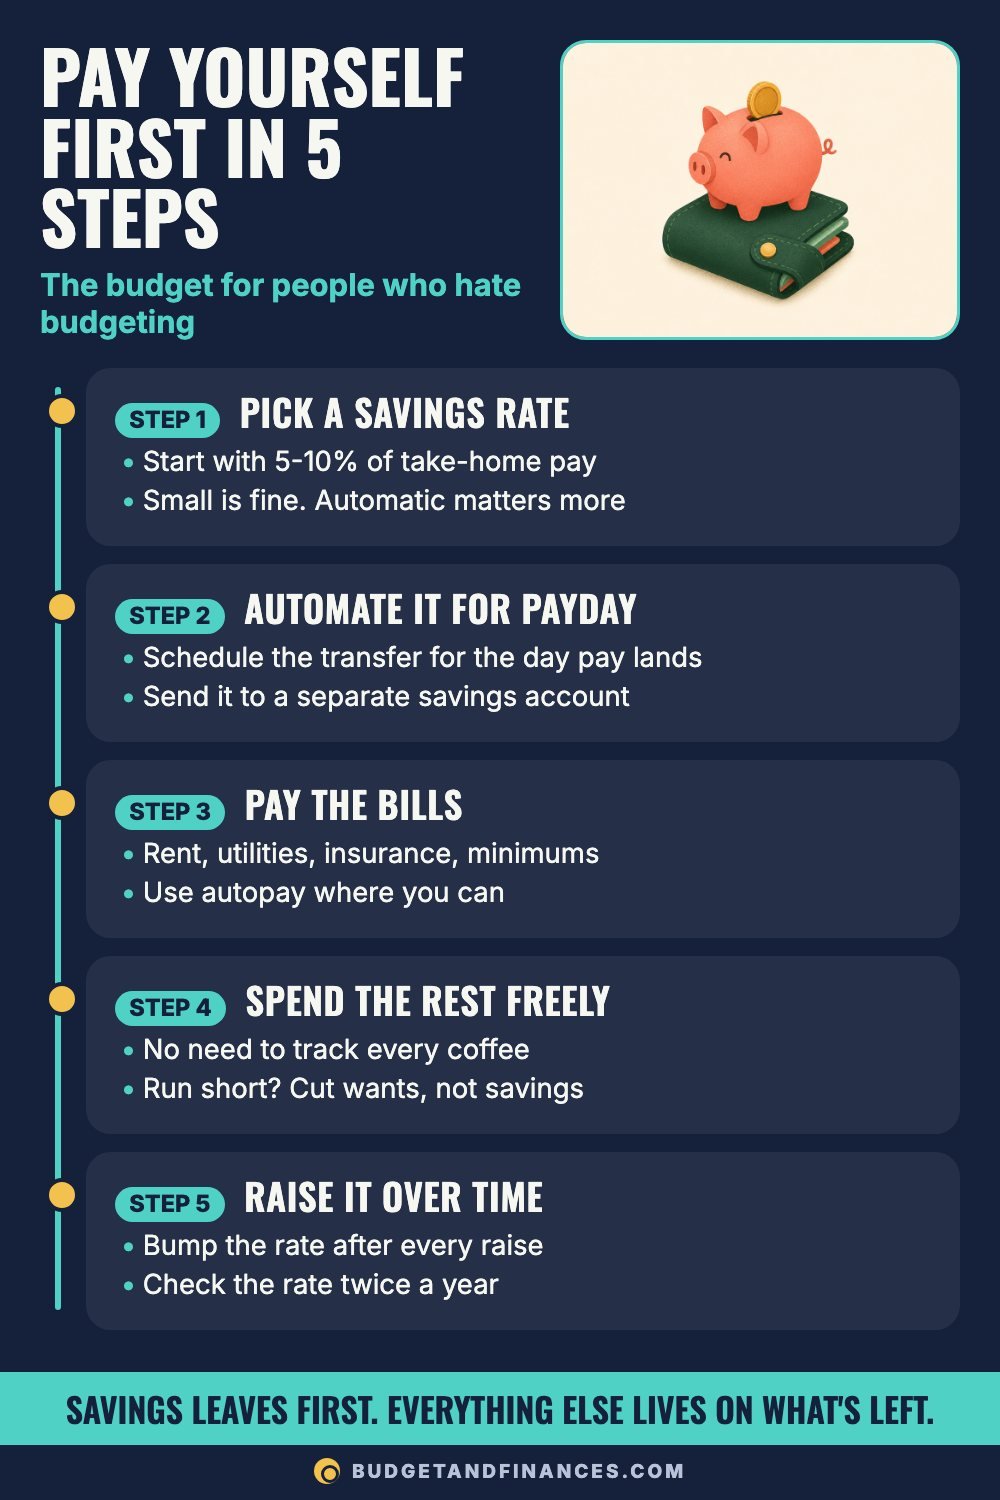
- Step 1: Pick a savings rate
- Step 2: Automate it for payday
- Step 3: Pay the bills
- Step 4: Spend the rest freely
- Step 5: Raise it over time
- A pay yourself first budget on $3,000 a month
- How much to pay yourself first at different incomes
- Tips to make it stick
- Try the 26-paycheck savings chart
- Common mistakes
- FAQ
How pay yourself first works
Most people budget in this order: pay bills, spend, then save what’s left. The trouble is that spending expands to fill whatever is available.
Paying yourself first reverses it:
- Savings comes out first, automatically.
- Bills get paid.
- You spend the rest freely.
Savings leaves first. Everything else lives on what’s left. The money you never see in checking is the money you don’t miss.
Step 1: Pick a savings rate
Start with 5-10% of your take-home pay. If that’s too much right now, start smaller. Even $20 a paycheck builds the habit.
Small is fine. Automatic matters more than the amount.
Step 2: Automate it for payday
Schedule a recurring transfer for the day your pay lands. Send it to a separate savings account, ideally at a different bank. Money that’s one tap away in the same app is easier to pull back on a whim.
Give the account a name that matches its goal, like Emergency Fund or New Car. It’s harder to spend a goal than a generic savings balance.
Step 3: Pay the bills
Next come the fixed costs: rent, utilities, insurance and minimum debt payments. Put them on autopay where you can, timed shortly after payday.
Step 4: Spend the rest freely
This is the part people like. What’s left after savings and bills is yours. There’s no need to track every purchase. If you later want every category on one page, our free monthly budget template lays it out.
The one rule: if you run short before payday, cut wants, not savings. Skip a takeout night instead of pausing the transfer.
Step 5: Raise it over time
Check your savings rate twice a year. Every time you get a raise, bump the rate before you get used to the bigger paycheck. Moving part of a raise to savings right away is much easier than cutting back later.
A pay yourself first budget on $3,000 a month
Here’s what it could look like on $3,000 a month in take-home pay, with 15% going to savings first:
| Category | Share | Amount | What it covers |
|---|---|---|---|
| Savings (paid first) | 15% | $450 | Automatic transfer on payday to emergency fund and goals |
| Housing | 35% | $1,050 | Rent or mortgage, renters or home insurance |
| Utilities and phone | 8% | $240 | Electric, water, internet, phone plan |
| Groceries | 12% | $360 | Food and household basics |
| Transportation | 12% | $360 | Gas, car insurance, maintenance |
| Debt minimums | 8% | $240 | Credit card, car and student loan minimums |
| Everything else | 10% | $300 | Eating out, fun, clothes, whatever you like |
| Total | 100% | $3,000 |
On payday, $450 leaves for savings. The fixed costs above take another $2,250. The last $300 is spending money you don’t have to track.
If 15% feels like too big a jump, start at 5%, which is $150 a month on $3,000, or 10%, which is $300. You can raise it as bills go away or pay goes up.
How much to pay yourself first at different incomes
There’s no single right savings rate. A common pattern is for the savings share to grow as income grows, while housing takes a smaller slice. Here are sample budgets on three monthly take-home incomes:
| Category | $2,500 | $4,000 | $6,000 |
|---|---|---|---|
| Savings (paid first) | 5% ($125) | 10% ($400) | 15% ($900) |
| Housing | 40% ($1,000) | 35% ($1,400) | 30% ($1,800) |
| Food | 15% ($375) | 13% ($520) | 12% ($720) |
| Transportation | 13% ($325) | 12% ($480) | 12% ($720) |
| Bills and insurance | 12% ($300) | 10% ($400) | 9% ($540) |
| Debt payments | 8% ($200) | 10% ($400) | 10% ($600) |
| Spending money | 7% ($175) | 10% ($400) | 12% ($720) |
Use this as a starting guide, not a rule. Start where you are. Even 5% paid first is a real habit.
Tips to make it stick
Start tiny. $20 a paycheck is enough to begin. Raise it once the transfer stops feeling strange.
Keep savings out of sight. An account at a different bank is harder to raid.
Name the account. A goal name makes the money feel spoken for.
Grab any retirement match. If your employer matches retirement contributions, contribute at least enough to get the full match. That’s part of paying yourself first too.
Save part of every windfall. Tax refunds, bonuses and cash gifts can go straight to savings before they get spent.
Raise it with raises. When your pay goes up, move part of the increase to savings right away.
Try the 26-paycheck savings chart
If you’re paid every two weeks, this chart turns paying yourself first into a simple challenge. It has 26 boxes, one per paycheck.
The first box is $5. Each box after that goes up by $5, so paycheck two is $10, paycheck three is $15, and the last box is $130. Move each box’s amount to savings the day you get paid and color it in.
Fill in all 26 boxes and you’ll have saved $1,755. Compare that with a flat $20 per paycheck, which adds up to $520 over the same 26 paychecks.
Common mistakes
Leaving savings in checking. If it sits in the same account as spending money, it usually gets spent. Move it to a separate account.
Picking a rate you can’t keep. A 20% transfer you cancel in month two saves less than a 5% transfer that runs all year.
Pausing savings when money gets tight. Cut wants first. Pause the transfer only if bills truly can’t be covered.
Forgetting irregular bills. Car repairs and yearly subscriptions still come due. Consider part of your savings a sinking fund for those.
Never raising the rate. A savings rate set once and left alone falls behind as your income grows.
FAQ
Is pay yourself first a real budget?
Yes. It’s a simpler kind of budget. You decide on savings and cover fixed bills, then spend the rest without tracking categories.
Should I pay myself first if I have credit card debt?
Many people still save a small starter emergency fund first, so a surprise doesn’t go back on the card, and send extra money to debt after that. Minimum payments always come before extra savings.
Where should the money I pay myself go first?
A common order is a starter emergency fund first, often $1,000, then a fuller emergency fund of 3-6 months of expenses, then longer-term goals. If your employer offers a retirement match, many people contribute enough to get it along the way. You can also split one transfer into two accounts, like $100 for emergencies and $50 for a vacation.
What if my paycheck changes from month to month?
Use a percentage instead of a fixed dollar amount, or set the transfer based on your smallest typical paycheck. When a bigger check comes in, move a little extra by hand. The habit matters more than hitting the same number every time.
Does a 401(k) contribution count as paying yourself first?
Retirement contributions taken from your paycheck are savings that happen before you can spend the money, so they follow the same idea.
This is general education, not personal financial advice.